Home Blog Page 12

Global Consumer Research Illustrates Future Trends In AI

Global Consumer Research Illustrates Future Trends
Rohan Tambyrajah, PHD.

A study by PHD in partnership with WARC finds that total agent-facilitated consumer spending will triple from $944 billion this year to $3.35 trillion in 2030. While consumers will still make most purchase decisions on their own in the next few years, AI agents will increasingly shape what gets seen, shortlisted and bought, and will increasingly mediate the boring, complex or repetitive tasks along the way.

Marketing is operating in an age of abundance. Today’s consumers face more content and choices than they have the attention or means to manage. AI agents are emerging as fundamental tools to help consumers cut through the noise and make decisions faster. The research reveals how quickly they are reshaping the customer journey.

As decision-making increasingly evolves from human consumers to machine intermediaries, this study explores the scale, timeline and implications for brands, agencies and the wider marketing ecosystem.

Rohan Tambyrajah, Worldwide Chief Strategy Officer, PHD, said, ‘This research brings category level empiricism to the open-ended industry conversation about the growth opportunity with consumer facing AI and Agentic AI. It underscores the need for brands to design for both meaning and machine logic, and through Four Modes Framework offers marketers practical guidance on how best to implement against a category-level business case.’

James McDonald, Director of Data, Intelligence & Forecasting, WARC, and author of the research, said, ‘This landmark study finds that agentic AI is already facilitating the path to purchase for many consumers, and will become deeply embedded over the coming years to influence $3.35 trillion in household expenditure by 2030.

‘This is true not just in high-frequency categories such as travel, CPG, and utilities, but increasingly more so in sectors that have traditionally leveraged brand marketing as a core strategy. By mapping adoption across product sectors, markets and media, our research ensures practitioners are not caught flat-footed as they approach the new frontier.’

Methodology Of The Research

The research draws on data provided by Acxiom and uses a weighted index approach to evaluate key factors such as decision complexity, transaction value, purchase frequency, data availability, media mix, and market regulation to make a holistic assessment of how much consumers will spend on AI channels in 2026 and 2030. The analysis covers the global viewpoint of ten markets: Australia, Brazil, China, France, Germany, India, Mexico, South Korea, UK & US. Additionally, it includes industry expert views and category analysis.

Key findings from the research outlined in ‘From abundance to agents: how the delegation of choice is transforming marketing’ are:

Categories And Markets Leading On Agentic AI Consumer Spend

Agentic AI, artificial intelligence systems that understand goals, plans steps, and act autonomously, are making their mark on high-frequency categories like travel and transport, food, media and publishing. By 2030, AI-facilitated spending will surge across all industries, especially where purchases are frequent and data-rich.
The top three markets for agentic AI consumer spending in 2030 will be:

US: The US will lead agentic AI spending at $1.1trn (31.9% of the global total), driven by consumers already comfortable with digital commerce and brands with the resources to deploy agents at scale.

China: China will be the second-largest market at $505.8bn (15.1% of global spend), powered by high platform integration, government support, and consumers ready to embrace delegated commerce.

UK: The UK will capture 3.9% of global agentic AI spending ($131.2bn), driven by strong talent, major investments, and government backing for AI-led transformation.

How Agentic AI Will Affect Consumer Spending: Introducing The Four Modes Framework

Agentic AI will not impact all industry categories evenly. PHD’s Four Modes Framework defines where marketing must evolve as brands extend focus to influencing machines.

Each mode of marketing requires strategy, capability design and creativity. All four will coexist, with their importance varying by category, purchase occasion and customer journey stage.

The framework serves as a navigation tool to see the category impact of agentic AI on marginal purchasing decisions in 2026 and 2030, while recognising that brand advertising, salience, and equity remain fundamental to success.
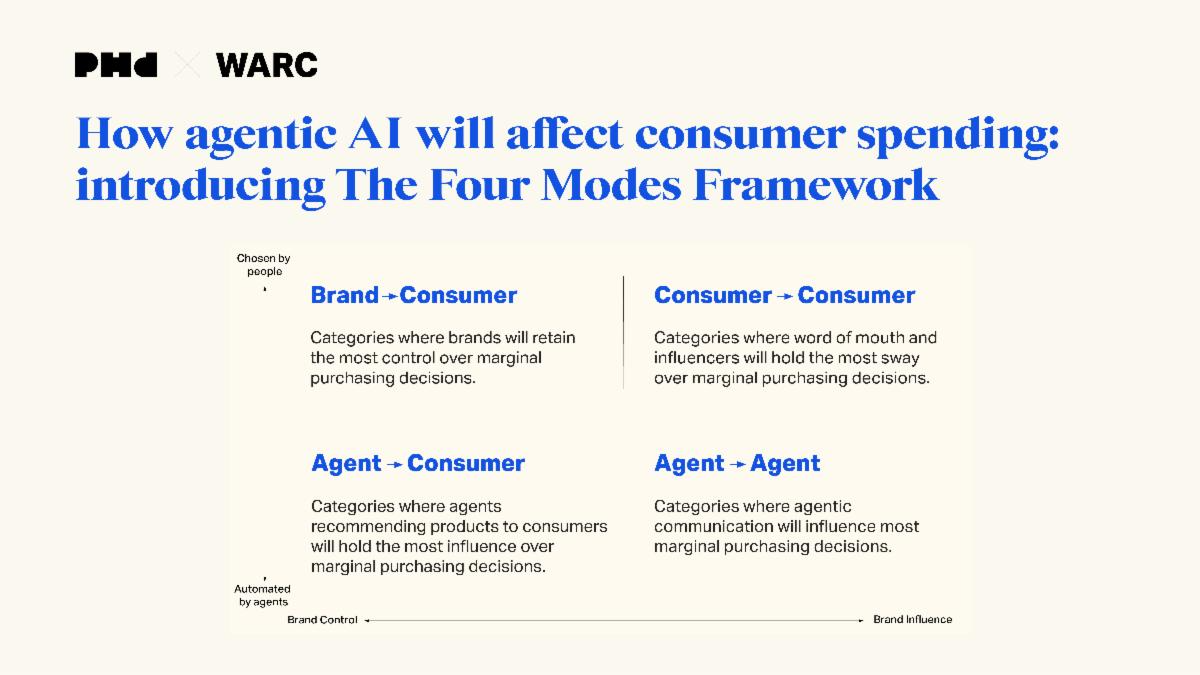
Agent → Agent

Agent adoption will surge where purchases are repetitive, searchable, and measurable, not necessarily high-volume or low-value, just routine enough for AI to own the entire journey.

The three industry categories where agentic AI will have the greatest impact are:

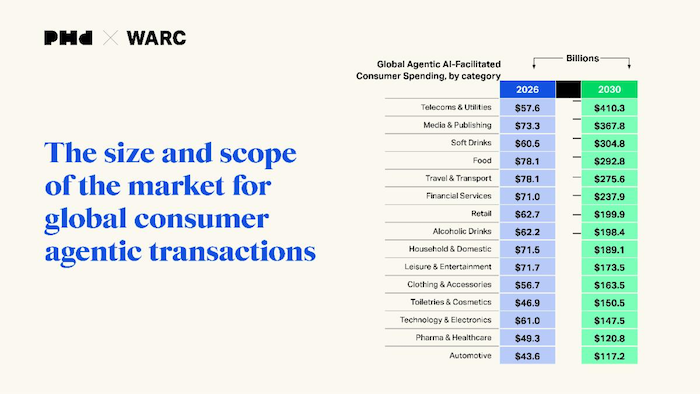
1. Telecoms and utilities will grow 611.9% from $57.6 billion in 2026 to $410.3 billion by 2030, making it the largest category for AI agents. Information-dense, frequent billing, and comparison-led contract switching make these infrequent but high-value purchases ideal for AI delegation.

2. Financial Services decisions are too sensitive to fully delegate, but too complex not to be agent-assisted. Total agent-facilitated consumer spending will increase 235.3% to $237.9 billion by 2030.

3. Travel and transport will lead agent-facilitated spending at $78.1 billion in 2026, surging 252.8% to $275.6 billion by 2030 as AI agents take control of discovery, planning, and booking.

Agent → Consumer

1. Alcoholic Drinks: This category is habitual and identity-driven, brand loyalty still rules. AI agents will influence $62 billion in spending in 2026, advising on party ideas, drink pairings, and occasions. By 2030, agentic spending will grow 219.0% to $198.4 billion as agents dominate both replenishment and discovery.

Soft Drinks: Starting small at $60.5 billon in agent-influenced spending in 2026, it will see massive growth of 403.5% to $304.8 billion by 2030. Habit-driven, low-value replenishment is perfect for AI automation: optimising price, convenience, and repeat purchasing.

2. Food: This category is primed for early use of agentic AI thanks to is high frequency, low decision complexity. Agents will influence $78.1 billion globally in 2026, surging 274.8% to $292.8 billion by 2030.

3. Media & Publishing: At $73.3 billion, this category is already one of the most impacted by agentic AI. Subscriptions, recommendations, and content consumption are digitally native and measurable. By 2030, agentic AI spending will increase 401.8% to $367.8 billion.

4. Retail: will see agent-facilitated spending grow 218.7%: from $62.7 billion in 2026 to $199.9 billion in 2030 driven by omnichannel shopping and AI comparison. The challenge for retailers will be to remain part of the consumer shopping journey, not just a fulfilment provider.

Brand → Consumer

High-value, infrequent purchases such as automobiles, electronics, and categories with privacy constraints such as pharma and healthcare, leave less room for agentic AI transaction. Trust is important as consumers must feel confident before delegating expensive or privacy-sensitive decisions.

Consumer → Consumer

Categories such as toiletries and cosmetics, clothing and accessories are heavily influenced by word of mouth and creators and are less affected by agentic AI than others. The impact may be smaller, but it won’t be completely absent.

The Brand Imperative

Brands must learn new skills to successfully market to machines. The shift to agentic AI will require marketers to have:

– A strong foundation of structured, machine-readable data.
– Distinctive and differentiated brand assets.
– A unified brand story that resonates with both humans and AI interfaces.

‘From abundance to agents: how the delegation of choice is transforming marketing’ report is available to read in full here.’

WARC
https://www.warc.com
What Are The Arguments For And Against Brands Staying Neutral?

What Are The Arguments For And Against Brands Staying Neutral?
Willem Steenkamp, Flow Communications.

Willem Steenkamp, Flow Communications’ senior writer and editor, asks: should brands stay neutral in our divided world? Whether or not a brand should take a public stance on social or political issues is no longer a simple marketing decision. It is a fundamental strategic dilemma.

As our world becomes increasingly polarised, the pressure on organisations to act as moral agents has intensified. However, the risks associated with standing on principle, or staying silent, are also significant.

So what are the arguments for and against brands staying neutral?

For: Silence As A Strategic Choice

Avoiding alienation: in a deeply divided society, taking a stance on an issue almost inevitably alienates a portion of the customer base. Neutrality allows a brand to remain a ‘broad church’ for consumers.

The risk of being seen as hypocritical: if a brand champions gender equality but has a gender pay gap, for example, or promotes sustainability but has a high carbon footprint, the backlash can be far more damaging than silence.

Respecting internal diversity: a company may comprise employees with various personal beliefs. Taking a public stance may marginalise or silence staff who hold dissenting views.

Guarding against mission creep: a brand’s true social contribution is perhaps through its core business, creating jobs, paying taxes and driving economic growth, and it should not be distracted by social media trends or geopolitics.

Against: Why Neutrality Is A Mistake

The belief-driven customer: data increasingly show that younger consumers, Gen Z and Millennials in particular, choose brands that align with their values. A principled stance builds brand loyalty and differentiation.

ESG drives value: corporate environmental, social and governance (ESG) criteria are vital for attracting investment and talent. Committing to social justice or sustainability shows a brand grasps its impact on the communities in which it operates.

Corporate influence: by taking a stance on issues such as climate change or human rights, brands can drive change that individual consumers cannot. With great power, some argue, comes great social responsibility.

Authenticity and ‘being right’: brands staying silent on major issues risk being seen as uncaring or profit-obsessed. Taking a stand, even if it causes short-term friction, can cement a brand’s legacy as being authentic and courageous.

Two Examples

In 2022, outdoor recreation clothing brand Patagonia declared that ‘Earth is our only shareholder’, putting 2% voting shares into a trust and the remaining 98% non-voting shares into a vehicle that gives 100% of profits, estimated at $100-million a year, to land conservation and environmental activism. Patagonia is seen by many as embracing a ‘new capitalism’.

In 2023, brewer AB InBev partnered with transgender influencer Dylan Mulvaney to boost inclusivity (and flagging Bud Light sales). This campaign sparked an enormous conservative backlash, and when the brewer backtracked, it created a second backlash, from the LGBTQ+ community. AB InBev lost a projected $1 billion in sales and even more market share.

The differences are (1) motive and (2) resolve. On the one hand, Patagonia put its money where its mouth is; its motive was climate activism and its determination was solid. On the other hand, AB InBev wanted to increase sales, and then lacked the courage of its convictions when things went sideways.

Now consider this. The Havas Meaningful Brands 2025 report, which mined 460 000-plus consumer insights across more than 30 markets, found that 70% of people believe ‘brands should be doing much more for the good of society and the future of our planet, communication is not enough’. And neglecting these expectations is a risk, with 46% of people saying they have ‘stopped buying from brands that do not respect the planet or society’.

Silence may be golden. But it may also be fool’s gold.

FLOW COMMUNICATIONS
www.flowsa.com

Making Loyalty Easier To Use Makes Saving Easier

Making Loyalty Easier To Use Makes Saving Easier

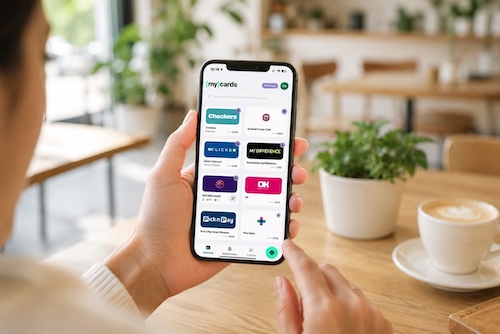
Byron Rode, co-founder and CEO of Ignis Labs (part of Glynt) illustrates why loyalty rewards are slipping through the cracks. July is Savings Month, when we should all look for opportunities to make every rand stretch a bit further. Your loyalty programmes can help with this, but only if they are easy to use.

It is month-end and you are standing at the till with your full trolley, packing each item while the queue grows ever longer behind you. Then the question: ‘Do you have a loyalty card?’ You are sure you have signed up. Where is the card? You start digging around your bag and leafing through your wallet. It must be here somewhere. Maybe on your phone? Did you ever get round to downloading the store’s app?

You sigh. ‘No, I don’t have a loyalty card. Let’s just finish up.’ It is a small moment in a busy day, but when it happens every time you buy something, all those lost loyalty points and forgotten rewards stack up. Think about all those trips to the supermarket, the pharmacy or the petrol garage. Whenever you abandon your search for that scratched-up card, you are potentially leaving money on the table.

South African consumers have wholeheartedly embraced loyalty programmes. In the latest Truth & BrandMapp loyalty research, 77% of consumers say loyalty programmes influence where they buy groceries, while 41% prefer shopping at retailers where they already belong to the programme.

However, fitting them into real life is another matter. That matters because loyalty has changed. It is not just about a free coffee with every 10 purchases. With our budgets increasingly squeezed tight, those reward points can make a real difference to your financial planning and shopping habits. You might think it is only a few points, but the reality is that loyalty works a lot like compound interest. One forgotten scan does not amount to much, but a year’s worth of missed discounts and rewards is a different story.

But forgotten cards are only part of the problem. Rewards also slip through the cracks when we can not remember which retailer has which programme, do not want to download yet another app, or simply do not have the time or headspace to keep track of multiple loyalty schemes. None of these feels significant in isolation, but together they create enough friction for consumers to miss out on value they had every intention of earning.

The issue is that loyalty has become surprisingly difficult to manage. As consumers face increasing financial pressure, and rewards programmes grow more attractive, we have not one programme, but many. And each of these programmes has its own card, app, barcode or login. Rather than making loyalty simpler, we have gradually added more layers of complexity and friction to something that is supposed to make life better for us.

It’s a challenge we have seen first-hand, where many users tell us they do not need more loyalty programmes, they simply need an easier way to manage the ones they already belong to. The average consumer belongs to nine different loyalty programmes. Managing them, not joining them, has become the real challenge.

For years, the conversation around loyalty has focused on bigger rewards, richer benefits and signing consumers up to more programmes. But I believe the next evolution of loyalty is not about offering more, it is about removing the friction.

The brands that will win are those that make earning and redeeming those rewards feel effortless. We have already seen this happen in banking, where digital wallets and contactless payments have transformed everyday transactions, and we can expect loyalty to follow the same path. Consumers do not want to think about loyalty every time they shop. They simply want it to work.

The research already points in this direction, with 45% of consumers now using virtual loyalty cards because they are more convenient and accessible. People increasingly expect everyday experiences to be seamless, and loyalty should be no different.

That is the challenge we are working to solve. Not by asking consumers to join another loyalty programme, but by helping them get more value from the programmes they already use. People want the rewards they are entitled to without carrying a wallet full of plastic or swiping through a dozen retailer apps at the checkout.

Having all your loyalty cards in one easily accessible place makes it so much easier to collect those points and reap the rewards. That’s how you can turn the loyalty you’ve already earned into savings you can actually use.

GLYNT GROUP
https://glyntgroup.co.za/

Data Should Be Rebalanced, Not Abandoned

Data Should Be Rebalanced, Not Abandoned
Tafadzwa Muzuwa, Machine.

Tafadzwa Muzuwa, Strategy Director at Machine, discusses looking beyond data, and why growth is still human-led. For the last decade, ‘data‑driven decision making’ has been treated as the gold standard for growth. Measure everything. Optimise relentlessly.

Follow the numbers. And yet, despite better dashboards and more sophisticated analytics than ever before, many organisations are struggling to grow in ways that feel meaningful, differentiated, or enduring.

The problem is not data itself. It’s the belief that data alone can tell us where to go next. As Harvard Business Review cautions, leaders often either ‘take the evidence presented as gospel or dismiss it altogether. Both approaches are misguided.’

Data is exceptional at explaining what has already happened. It helps us understand behaviour, refine processes, and assess performance. What it cannot do is imagine new futures. Left unchecked, an over‑reliance on data risks narrowing ambition, rewarding short‑term efficiency over long‑term value, and blinding organisations to opportunities that don’t yet show up on a chart. True growth happens when data informs decisions, but human insight sets the destination.

When Data Becomes A Constraint

Nike’s recent history offers a cautionary tale. Under CEO John Donahoe, the brand doubled down on a direct‑to‑consumer (D2C), data‑centric strategy. Wholesale relationships were cut back, marketing became increasingly performance‑led, and customer relationship management (CRM) data was elevated as a primary growth lever. Initially, the model appeared to work, particularly during the pandemic-driven boom of 2020.

But from 2021 onwards, cracks began to show. Nike’s cultural relevance softened, competitors gained ground, and relationships with key partners deteriorated. Despite abundant consumer data, the brand lost mental availability and momentum. Eventually, leadership changed, with longtime Nike veteran Elliott Hill returning the organisation towards its roots.

The lesson isn’t that D2C or data-driven CRM are inherently flawed. It is that when data is allowed to override brand intuition, cultural understanding and audience empathy, even the strongest brands can drift off course.

Growth Doesn’t Always Announce Itself In The Data

By contrast, some of the most powerful growth moments in business came from decisions that were not data-led at all. The NFL’s transformation of the Super Bowl halftime show is a classic example. For years, halftime was a moment of disengagement, viewers tuned out, grabbed snacks, or switched channels. Then, in 1993, the NFL made a bold call to feature Michael Jackson. The move was not driven by existing performance metrics; it was based on a deep understanding of cultural behaviour.

The result is the now-famous ‘Halftime Effect’: halftime became a headline act, viewership surged, and performers experienced massive boosts in popularity and sales. Data later confirmed the impact, but it did not predict the opportunity, human insight did.

Vision First, Data Second

Perhaps the most striking example of insight-led growth comes from outside traditional brand thinking altogether. Since the early 1990s, South Korea has deliberately invested in exporting its culture, from K‑pop and K‑dramas to food, fashion, and technology. This was not driven by optimising existing industries, but by a clear, unified vision of national identity and influence.

The results speak for themselves. Cultural exports now contribute tens of billions of dollars to the economy, major global acts rival multinational corporations in GDP impact, and tourism has flourished as a direct outcome of cultural engagement. Data followed the vision, not the other way around.

Rebalancing The Equation

The opportunity for organisations today is not to abandon data, but to rebalance their relationship with it. That starts with better questions:

– Where might data be giving us clarity, but not meaning?
– What human truths, cultural shifts, or emerging behaviours sit outside our dashboards?
– How do we create space for intuition, challenge, and imagination alongside metrics?

Growth demands courage. The courage to trust human judgement, to think beyond optimisation, and to remember that the most valuable decisions often start as informed leaps, not statistical certainties.

Data should light the path and confirm the validity of routes. But it is people who still need to decide where the journey leads.

MACHINE
www.thisismachine.co.za

Creative Education Has A Broader Responsibility

Creative Education Has A Broader Responsibility
Anthea Whitehead, AAA School of Advertising.

According to Anthea Whitehead, Cape Town Campus Manager, AAA School of Advertising, across music, fashion, film, design, gaming, and digital innovation, African talent continues to influence global culture in profound ways. Our challenge is not generating world-class ideas; it is ensuring that the people behind the ideas retain enough ownership to build sustainable economic value from them.

This distinction matters because creativity has become one of the world’s most valuable commodities. South Africa’s cultural, creative and sports industries already contribute approximately 3.9% of national GDP. Yet, too often, our creatives are generating commercial success while receiving only a fraction of the long-term value for themselves.

This is not simply about recognition. South African agencies continue to perform on the world’s biggest creative stages. African musicians shape global music charts. Designers influence international fashion. Nigerian film continues its remarkable expansion, while African coders and developers are redefining global gaming and technology.

The problem is that ownership frequently follows a different path from creation.
Many global businesses source creative talent from Africa because it is highly skilled, adaptable, and competitively priced. This creates valuable opportunities, but it also exposes an imbalance. Too often, African ideas are commercialised through international platforms, investment, and ownership structures, leaving relatively little long-term value on the continent itself.

The conversation therefore needs to move beyond talent. We should be asking how Africa builds stronger systems around creativity, including education, funding, intellectual property protection, entrepreneurship, commercialisation, and distribution.

Investment remains one of the biggest obstacles. While businesses readily fund engineering, medicine, and other traditional professions, creative careers are often viewed as higher risk or less economically important. This perception ignores the growing contribution of creative industries to economic growth and employment, as well as their ability to drive innovation across sectors.

Ownership is equally important. Young creatives often understand how to develop compelling ideas, but far fewer understand how to protect, licence, and commercialise their ideas over time.

Creative education therefore has a broader responsibility than teaching technical skills alone. Students need to understand strategy alongside storytelling, entrepreneurship alongside execution, and commercial thinking alongside creative excellence. They need exposure to real industry challenges where they learn not only how to solve problems, but also how to create lasting value from their solutions.

The recent success of AAA students in the L’Oréal Brandstorm competition illustrates this shift. Their achievement emerged from rigorous research, relentless creative refinement, commercial viability, and a deep understanding of human behaviour. While the competition provides valuable global exposure, it also highlights an important lesson for the wider industry: great ideas become truly valuable when they are developed through disciplined thinking and supported by the structures that allow them to grow.

This means that building stronger partnerships between educators, industry, and brands is imperative. Students benefit enormously from working on live briefs, learning from practising professionals, and understanding how creativity operates within real commercial environments. At the same time, businesses gain access to fresh thinking while helping develop the next generation of creative leaders.

Africa also has something international players cannot replicate: deep local understanding. Creative work developed for African audiences cannot simply be imported or translated. It requires genuine cultural insight, linguistic understanding, and an appreciation of local nuance. African creators are uniquely positioned to solve African challenges while producing ideas with global relevance.

The future of Africa’s creative economy will not be determined by whether the continent can produce exceptional talent. It already does. The real opportunity lies in building the investment, partnerships, intellectual property frameworks, and commercial confidence that will allow African creators to own more of what they create.

When this happens, Africa will not only shape local and global culture. It will retain far more of the value it generates.

AAA
https://aaaschool.ac.za/

Why Different Rules Apply To The South African Media Landscape

Why Different Rules Apply To The South African Media Landscape
Influencer content naturally bridges the gap between branded assets and user-generated content.

Nicola Ashe, Strategic Business Director at digital agency TDMC (The Digital Media Collective), and Zandile Dlamini, TDMC’s Strategic Content Partnerships Director, unpack the valuable role customer content plays within a brand’s paid media strategy, and how forward-thinking brands and agencies are deploying them to maximise returns.

User-Generated Content (UGC) vs Content Creation

Most brands now work across three distinct content types:

Brand-produced content: Developed through creative agencies to build awareness and communicate the brand’s key message. ‘Brand-produced content is art-directed, copy-approved, visually consistent and brand safe. It builds awareness, establishes identity, and positions the brand in a category. It is built to communicate,’ said Ashe.

Influencer content: Here creators are selected strategically and given the freedom to create authentically while still working towards a campaign objective.

UGC: Genuine customer content that acts as social proof and can also be licensed by a brand and amplified through paid media. ‘True UGC content is organic in origin: created by customers, community members, or fans for their own audience not for the brand,’ said Ashe. ‘This distinction matters because audiences can tell – and in South Africa particularly, the penalty for inauthenticity is steep.’

As Ashe points out, UGC content answers the question that brand content fundamentally cannot: ‘But does it actually work?’. ‘The rough edge of a shaky camera, an unscripted reaction, a real kitchen or a real trial, these are not imperfections. They are trust signals,’ said Ashe.

Dlamini said influencer content naturally bridges the gap between branded assets and UGC, influencers help establish credibility and trust, while UGC reinforces and scales that trust by showing real customers having similar experiences. ‘One of my key measures of a successful influencer campaign is, of course, engagement. But what excites me even more is when consumers start using the same hashtags as our influencers and create their own content around the campaign,’ said Dlamini. ‘That’s when we know we’ve done a good job. It shows the audience hasn’t just consumed the content; they’ve engaged with it enough to become advocates themselves and that’s where influencer content helps spark genuine UGC.’

Perfecting Paid Media Strategy

A mature paid media strategy deploys each content type where it performs best. Brand content drives awareness at the top of the funnel, influencer content adds credibility in the mid-funnel, and UGC closes the loop at the mid-to-lower funnel, where intent is highest and scepticism is strongest.

‘The mistake most agencies make is treating these as interchangeable or, worse, using influencer and UGC purely as a cost-reduction strategy. At TDMC, we integrate all three within a broader media strategy that understands each content type’s job,’ said Ashe.

Data And Authenticity

‘Authenticity’ may have become marketing’s most overused word, but behind the buzzword the performance data is compelling. Studies consistently show UGC and authentic influencer-based ads outperform brand-produced equivalents across click-through rates, cost-per-acquisition, and purchase intent, particularly for audiences already in a consideration or decision mindset.

Dlamini says at TDMC they have a unique approach to influencer content, taking advantage of engaging influencers they trust and giving them the freedom to put their own spin on the content they create. ‘TDMC actually sits in a small grey area between brand and influencer, we use and pay influencers to create content for their own channels about the brand, but we allow them to create with their own lens within brand guardrails. This is fundamentally different to most influencer agencies who prefer to ’script’ the outcome.’

She says they identify influencers who have a good organic reach who can create within the confines of the brand brief but stay true to their own personality and audience. ‘That authenticity is key as this is where followers will spot a fake alignment from a mile away. For a consumer weighing up a purchase, a real person’s unscripted experience functions as social proof in a way that a polished brand video never can. The conversion lift this generates at the bottom of the funnel is where it earns its place in paid strategy,’ said Dlamini.

Critically though, authenticity cannot be manufactured. Audiences, and Meta’s ad algorithms, are increasingly sophisticated at detecting content that mimics UGC aesthetics without genuine authenticity behind it. Dlamini warns that brands who brief creators to ‘make it look like a real video’ are investing in a diminishing return. ‘The advantage comes from the real thing.’

The South African Landscape And Why Different Rules Apply

South Africa is not a proxy market for global trends. A deeply connected community culture, across WhatsApp groups, community Facebook pages, and informal review networks, means genuine peer endorsement carries more weight here than in markets where brand messaging is more readily accepted. Facebook remains a dominant paid media channel, particularly for audiences over 30. Language matters too. Content in Zulu, Sotho, Xhosa, Afrikaans, or everyday South African code-switching carries a resonance polished brand content rarely achieves.

As Dlamini points out, content done well taps directly into this unique cultural dynamic. ‘At TDMC, creator selection is never arbitrary. We match people to objectives, not just aesthetics, because the SA audience is too culturally connected and too sceptical of performative marketing for a misaligned voice to go unnoticed. We send content back if we feel a creator is forcing a version of themselves or creating inauthentic content. We work with many mass market brands, and we never work with someone we feel doesn’t understand the nuances of a brand, food or culture.’

Where Brands Go Wrong

The most common failure is process, not creative. Brands find content they want to use but have no rights agreement in place. Others over-specify briefs until the authenticity is briefed out. At TDMC, activation is built on 3 non-negotiables: a rights acquisition framework, a briefing approach that protects authenticity while meeting brand-safety requirements, and a paid adaptation process that optimises without sanitising.

‘The best briefs define the problem, not the execution,’ said Ashe. ‘A directive that says, ‘We need you to show how this fits into your morning routine’ produces more usable content than, ‘Please film a 30-second vertical video starting with a close-up of the product then cut into your kitchen saying…’. The latter produces a low-budget ad. The former produces authentic content.’

Placing Strategy Before Content

Looking ahead, UGC’s role as a trust signal will only become more valuable as AI-generated content saturates digital environments. ‘Brands that build campaigns that ignite UGC pipelines now are investing in an appreciating asset,’ said Ashe.

Where most agencies lead with a creator roster and work backwards to a strategy, Ashe says TDMC leads with a media objective and builds a content ecosystem around it. ‘That means each is being deployed at the right moment in the right channel to move the right audience,’ said Ashe. The result is a paid media offering where influencer-style UGC doesn’t replace influencer or brand production, it completes them, and where brands are building something more durable than a campaign, they are investing in a content ecosystem that compounds in effectiveness over time.

‘At TDMC, the question we ask every client isn’t ‘Should we use influencer-style UGC?’. It’s ‘Where in the customer journey is trust the missing ingredient?’. That question gets you to the right answer every time and it’s a very different conversation to the one most agencies are having,’ said Ashe.

As influencer and user generated content matures as a paid media discipline, the agencies that lead will be those treating it with the same strategic rigour as every other element of the media mix. And at the heart of that is understanding the consumer and building a connection between them and a brand, says Dlamini.

‘The biggest mistake agencies make is becoming disconnected from the consumer. At TDMC, we don’t have that problem because we are the consumer. We lead with strategy, we consider the full digital ecosystem, and we give creators the freedom to speak in their mother tongue, to their community, in a way that feels natural. We also refuse to box the mass consumer in. A mom who buys the product also likes humour, recipe content, lifestyle content, she contains multitudes,’ said Dlamini. ‘Our job is to reflect that. UGC is the bridge between brand and consumer, and we are the architects of that bridge.’

TDMC
https://tdmc.co.za/

Does The Marketing Industry Formula Still Work?

Does The Marketing Industry Formula Still Work?
Pieter Geyser, Humanz.

Pieter Geyser, commercial director at Humanz, has emphasised that roughly 10% of creative work drives approximately 95% of marketing value. You cannot predict which 10% in advance. And the entire apparatus of modern marketing efficiency, from hyper-targeted media to focus-grouped creative, is specifically designed to eliminate the conditions that allow breakthrough work to exist.

Creative and media were separated for billing reasons, not strategic ones. The holding groups know it. They are trying to fix it. And they are going to fail unless they change the one thing they are not willing to change.

The only formula that actually matters in modern marketing is the following: (Creative x Media) x (Quality x Quantity x Continuity).

Each element multiplies the other ones. Weaken any one of them and the whole system underperforms. Zero out any one of them and the whole system collapses.

To understand why the industry finds this formula so hard to execute, you have to understand how it deliberately separated the two most important variables in that equation, put them in different buildings, and charged clients twice for the privilege.

How The Divorce Happened

It did not start as sabotage. It started as a billing decision.

For most of advertising’s history, creative and media lived under the same roof. Full-service agencies handled both. They developed the idea and they placed the work. The relationship between the two disciplines was imperfect, occasionally dysfunctional, but fundamentally intact. The people making the ads knew where they were going. The people buying the media knew what they were buying.

Then, in the 1990s, the holding groups spotted an opportunity.

Media buying was becoming increasingly complex. The proliferation of channels, the rise of satellite television, and the early rumblings of digital created a genuine case for specialisation. Media agencies could aggregate buying power across multiple clients, negotiate better rates, and offer clients something that looked like scale and sophistication.

So WPP, Publicis, Omnicom, Interpublic, Dentsu and Havas began spinning their media operations out into separate entities. GroupM. Publicis Media. Omnicom Media Group. Initiative. Carat. The names became familiar. The structure became standard. And the separation became permanent.

What nobody said out loud at the time was that the real motivation had less to do with strategic logic and more to do with margin. Media buying generated revenue through volume and rebates. Separating it from creative allowed the holding groups to monetise both disciplines independently, build two sets of client relationships, and in many cases charge the same client twice for work that used to be done by one integrated team.

The client got a creative agency and a media agency. The holding group got two retainers.

For a while, nobody complained too loudly. The model worked well enough in a world where media was relatively simple and creative cycles were slow. You made the TV ad. You bought the airtime. You waited.

Then the internet arrived, and the separation stopped making any sense at all.

What The Divorce Actually Cost

In a digital world, creative and media are not separate decisions. They are the same decision, made in real time, continuously.

The format of the creative determines where it can run. The platform it runs on shapes how it needs to be made. The audience signal from the media informs what the next piece of creative should say. The performance of one execution tells you something about how to brief the next one. The feedback loop between making and placing is so tight that treating them as separate disciplines, managed by separate teams, briefed by separate client stakeholders, invoiced on separate contracts, is not just inefficient. It is structurally guaranteed to produce worse work.

Think about what happens in practice. A brand briefs its creative agency. The creative agency develops a campaign. The campaign goes into production. Weeks later, it lands with the media agency, who then figures out where to put it. The media agency has had no input into the creative. The creative agency has had no visibility of the media strategy. The two teams may never have met.

The creative is then served into placements it was never designed for, at a frequency the creative team never intended, to audiences the creative team never considered. Performance data flows back to the media agency. Some of it trickles across to the creative agency, usually too late and too filtered to be genuinely useful. The next campaign brief starts from scratch.

This is not a process designed to find the 10%. It is a process designed to produce the inoffensive middle, consistently, at scale, across two billing relationships. The client pays for the inefficiency and calls it a structure.

The Holding Groups Are Waking Up, Slowly

To their credit, the big six are not blind to this. They can read the room, and the room has been telling them for several years that the model is broken.

WPP has been the most vocal about it. Mark Read has spoken repeatedly about the need to integrate creative and media capabilities, and the acquisition and restructuring strategy of recent years reflects a genuine, if imperfect, attempt to move in that direction. VML, the merger of VMLY&R and Wunderman Thompson, is partly about building entities large enough to hold both capabilities credibly.

Publicis has taken a different approach, building Publicis Sapient as a technology and transformation layer that sits across its creative and media operations, attempting to create integration through data and technology rather than organisational structure.

Omnicom’s acquisition of Interpublic, announced in late 2024 and still working through regulatory approval at the time of writing, is the biggest structural bet in the industry’s recent history. The stated rationale involves data, technology, and AI capability. The unstated rationale almost certainly involves the recognition that scale and integration are now the same competitive advantage, and that neither holding group had enough of either on its own.

Dentsu has been restructuring its creative and media operations in various markets for several years, attempting to build what it calls an integrated growth model. Havas has positioned its ‘village’ structure, agencies clustered together in shared offices, as a form of integration by proximity.

IPG, before the Omnicom deal, had arguably gone further than most in genuinely integrating media and creative data capabilities through Acxiom and Kinesso. Every one of them is moving. None of them has solved it.

Why They Are Going To Struggle

Here is the problem, and it is a structural one that no reorganisation chart will fix on its own.

The holding groups separated creative and media because it was more profitable to run them as separate businesses. The incentive that created the separation has not gone away. It has just become more complicated to talk about.

When a holding group attempts to reintegrate creative and media, it immediately runs into a question it does not want to answer: which one leads? Which discipline sets the agenda, controls the client relationship, and ultimately determines how the budget is allocated?

Because here is what every senior person inside these organisations knows. Whoever controls the media budget controls the relationship. Media is where the volume is. Media is where the rebates are. Media is where the holding group’s most significant revenue sits. Creative, however strategically important, however central to the 10/95 rule, is the smaller number on the invoice.

So when a holding group says it is integrating creative and media, what it often means in practice is that the media agency is hiring some creatives. It is building a production capability. It is adding a creative director to the leadership team. The media logic still governs the operation. The media metrics still define success. The creative function is being absorbed, not genuinely integrated.

The holding groups are not doing this because they have had a philosophical awakening about the relationship between creative and media effectiveness. They are doing it because clients are starting to ask why they are paying two retainers for a process that produces worse results than a properly integrated team. And because a new generation of independent agencies and production companies, built from the ground up on integrated models, are starting to eat their lunch.

The threat is real. The response is real. But a restructure that is motivated by client retention rather than genuine strategic conviction tends to produce the appearance of change rather than the substance of it.

What This Means For You

If you are a CMO or a brand lead reading this, the structural problems of the holding groups are not your problem to solve. But they are absolutely your problem to navigate.

The agency model you inherited was designed around someone else’s billing logic. The question is whether you are willing to restructure around your own growth logic instead.

That starts with a few uncomfortable conversations. First, ask your creative and media agencies when they last worked in the same room on the same brief, at the same time, before anything went into production. If the answer is never, or rarely, or “we have a quarterly alignment meeting,” you do not have an integrated model. You have two separate agencies with a shared client.

Second, look at how creative performance data flows between your agencies. Does your media agency’s real-time performance data inform your next creative brief? Does your creative agency understand how their work is being placed and at what frequency? If those feedback loops don’t exist, you are running your marketing on incomplete information by design.

Third, question the volume of creative you are producing relative to the media budget you are spending. If you are spending significantly more on placing creative than on making it, you are almost certainly not producing enough executions to give the algorithm the signals it needs or to give the 10/95 rule room to work in your favour.

Fourth, and most directly: consider whether the two-agency model is still the right structure for the way marketing actually works today. That doesn’t necessarily mean firing anyone. It might mean restructuring contracts so that creative and media performance are measured against shared outcomes rather than separate KPIs. It might mean bringing one or both capabilities in-house. It might mean finding an agency partner that has genuinely, not nominally, built integration into how it operates.

The holding groups will tell you they have done this. Ask them to prove it. Ask to meet the creative and media teams in the same room. Ask to see how the data flows. Ask who leads when there’s a disagreement about where the budget goes. The answers will tell you everything you need to know.

Conclusion: The Formula Was Never The Problem

The formula is not complicated. Creative multiplied by media, multiplied by quality, quantity, and continuity. It is the foundation of every great brand campaign ever built. It is what the industry practised, imperfectly but instinctively, before it decided to reorganise itself around margin optimisation and call it progress.

The separation of creative and media did not happen because someone believed it would produce better marketing. It happened because someone believed it would produce better revenue. For a long time, for the holding groups at least, it did. The bill is now arriving for the brands that went along with it.

The good news is that the formula still works. The brands proving it right now are not doing something new. They are doing something old, with more creative volume, across broader reach, for longer than their competitors are willing to sustain.

The industry is waking up to what it broke. The question is whether you are willing to fix it on your terms, before someone fixes it for you.

This is part two of a two-part series. Also read part one, ‘The 10/95 Rule: Why Your Marketing Budget Is Funding the Search, Not the Solution’.

HUMANZ
www.humanz.com

Red & Yellow Announces Strategic Partnership

Red & Yellow Announces Strategic Partnership

A partnership between Red & Yellow Creative School of Business and the Association of Advertising Agencies of Nigeria (AAAN) will focus on the workforce changes affecting creative businesses across Africa, including AI adoption, talent retention, leadership development and the growing need for creative professionals who can compete in a global market. AAAN is an industry body representing Nigeria’s advertising and communications sector.

As a first step, Red & Yellow and AAAN will host an industry discussion on the reality of how agencies and marketers are responding to changing skills demands in Africa and globally.

Red & Yellow is a CHE-accredited private higher education institution headquartered in Cape Town, South Africa, and a member of Honoris United Universities. The school works across marketing, advertising, design, digital, business and corporate learning, equipping students and working professionals with commercial, creative and 4IR skills.

Verusha Maharaj, Managing Director of Red & Yellow, says the partnership demonstrates shared challenges across African creative industries. ‘Across Africa, agencies and marketing teams are dealing with similar pressures around talent, technology, leadership and competitiveness,’ said Maharaj. ‘This partnership gives us an opportunity to support a practical industry conversation about what creative businesses need now, and how education can respond more directly to those needs.’

Discussions with AAAN leadership have highlighted several issues facing Nigeria’s advertising and communications sector, including talent shortages, the poaching of skilled people, uncertainty around AI and future employability, and the need for more practical leadership and management training within agencies.

Similar concerns are being raised in South Africa, where agencies, brands and education providers are also looking at how to build talent pipelines that can keep pace with technological and commercial change.

‘Nigeria’s creative industry has enormous talent and ambition, but the skills required to stay competitive are changing quickly,’ said Lanre Adisa, CEO/ Chief Creative Officer
The Ark Group, and a representative with the AAAN. ‘Through this partnership, we want to support a thoughtful conversation around AI, leadership, employability and the capabilities agencies need to grow in a global market.’

‘The opportunity is to develop learning that is grounded in real workplace needs,’ said Melissa Opperman, Head of Life-Long Learning at Red & Yellow. ‘Creative businesses need people who can move faster, lead better and work with technology in ways that still serve strategy, creativity and business outcomes.’

The partnership is a step in Red & Yellow’s broader work across skills development, leadership training and future-of-work capability building, and shows the role South African education providers can play in supporting practical, industry-led learning across the continent.

RED AND YELLOW SCHOOL OF BUSINESS
www.redandyellow.co.za

South Africa’s Gaming Festival Unveils Revamped Visual Identity

South Africa's Gaming Festival Unveils Revamped Visual Identity

The new look for rAge, South Africa’s festival of gaming, technology, esports and geek culture, builds on the brand’s 24-year legacy while introducing a sharper, more future-facing identity.

Bold, immersive and unmistakably rooted in gaming culture, it reflects rAge’s evolution from a traditional gaming expo into a multi-day festival spanning cosplay, anime, entertainment and community.

The refreshed identity draws inspiration from retrofuturism, combining the visual nostalgia of gaming’s past with a modern interpretation of what the future could look like. The result is a flexible, energetic visual world designed to come alive across digital platforms, social content, event environments, merchandise and partner activations.

‘This is not a reset of the rAge people know and love. It is a visual upgrade,’ said Michael James, project director of rAge. ‘The new identity preserves the energy, curiosity and community that have always defined rAge while giving us a bigger visual world for the festival it is becoming.’

The rebrand also creates a more cohesive platform for rAge’s expanding ecosystem, giving partners, creators and communities more ways to participate in and contribute to the experience.

The new visual identity will roll out across rAge’s channels ahead of rAge 2026, taking place from 27 to 29 November at Fourways Mall in Johannesburg.

RAGE FESTIVAL
https://www.rageexpo.co.za

Nedbank IMC Announces Exclusive Radio Partner

Nedbank IMC Announces Exclusive Radio Partner
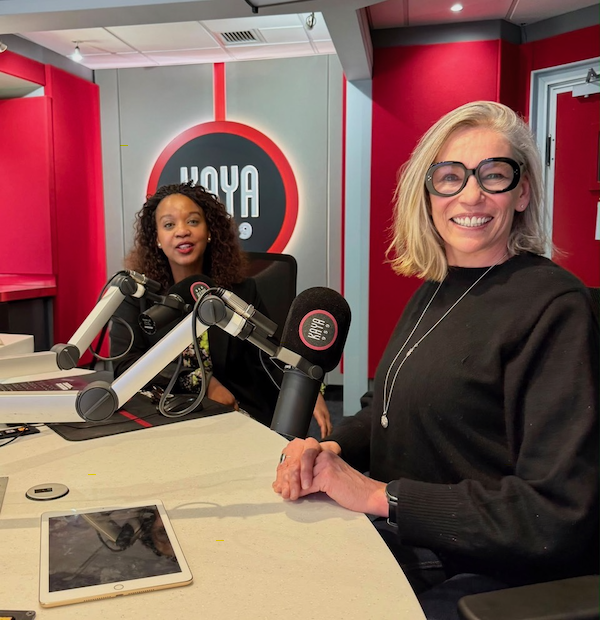
Tumi Rabanye, Kaya 959, and Dale Hefer, Nedbank IMC.

Kaya 959 is a leading Gauteng commercial radio station, connecting an influential audience through premium music, business, news, current affairs, culture and lifestyle programming. It has been announced as the exclusive radio partner of Africa’s Biggest Marketing Conference™, the Nedbank IMC 2026, marking a strategic partnership that will take the country’s most influential conversations on marketing, business and brand leadership beyond the conference stage and onto the airwaves. Modern Marketing is a proud media partner of the Nedbank IMC.

Held under the theme Shift Happens™. Are You Ready?, the Nedbank IMC 2026 will convene thousands of marketers, business leaders, entrepreneurs, agencies and innovators at Mosaïek Teatro in Johannesburg and online on 17 September 2026, exploring how organisations can remain relevant, resilient and commercially competitive in an era of constant disruption.

As the exclusive radio partner, Kaya 959 will transform the conference into an accessible national business conversation, connecting listeners with the ideas, people and strategies shaping the future of brands, business and economic growth.

More than simply promoting the event, Kaya 959’s partnership will shine a spotlight on the business of marketing through a series of exclusive live broadcasts, presenter-led interviews and digital content. Listeners will gain valuable access to some of South Africa’s most influential Chief Marketing Officers (CMOs), business leaders and industry pioneers through live interviews that unpack the commercial decisions, leadership thinking and innovations driving business success.

The station’s business, current affairs and digital platforms will explore how marketing creates sustainable growth, builds trust, influences customer behaviour, unlocks innovation and strengthens organisational performance. These conversations will bridge the gap between the boardroom and everyday business, making world-class marketing thinking accessible to entrepreneurs, professionals and decision-makers across Gauteng and beyond.

According to WhyFive Insights’ BrandMapp 2026, South Africa’s definitive study of the country’s top 30% of earners, Kaya 959 reaches 1.62 million regular listeners. This provides the Nedbank IMC with direct access to one of South Africa’s most commercially influential audiences, people who shape business, household and consumer purchasing decisions, while giving listeners valuable insight into how leading organisations compete, innovate and grow.

Tumi Rabanye, Head of Marketing at Kaya 959, says the partnership reflects the station’s ambition to become South Africa’s leading destination for commercially relevant cultural and business conversations.

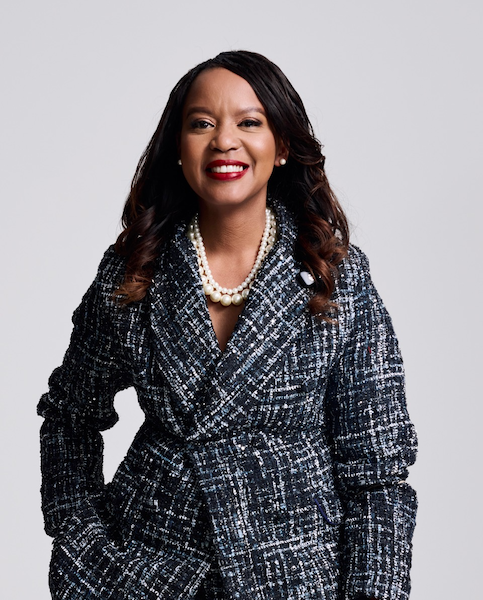
Tumi Rabanye, Kaya 959.

‘Marketing has become one of the most important drivers of business growth, innovation and competitive advantage. Through our partnership with Africa’s Biggest Marketing Conference™, Kaya 959 is creating a platform where listeners don’t simply hear about marketing, they experience the thinking behind the brands shaping our economy. By bringing some of South Africa’s most influential CMOs and business leaders directly to our audiences, we’re opening conversations that inspire innovation, leadership and commercial growth while reinforcing Kaya 959’s position as a trusted home for ideas that move business, culture and society forward.’

Nedbank IMC Announces Exclusive Radio Partner
Dale Hefer, Nedbank IMC.

Dale Hefer, CEO of the Nedbank IMC, says Kaya 959’s editorial credibility makes the partnership a natural extension of the conference’s purpose.

‘Kaya 959 gets what the Nedbank IMC is really about: marketing as a business issue, not just an advertising one. Their audience is commercially smart and influential, and this partnership helps us take the Marketing is Business® conversation well beyond the conference itself.’

The Nedbank IMC 2026 is expected to welcome approximately 3,000 delegates in person and online, supported by a wider community of more than 15,000 marketing professionals, reinforcing its position as Africa’s Biggest Marketing Conference™.

Tickets are available here.

Nedbank IMC
www.imcconference.com

This is Modern Marketing